For a business that uses most of its electricity in daylight, rooftop solar is one of the more predictable capital projects available. At the time of writing, well-sized commercial systems typically pay back in roughly four to seven years before tax relief. The result depends far more on when you use power than on how big your roof is, so that is where to start.
Size to your load profile, not your roof
A home installer's instinct is to fill the roof. For a business that is often the wrong answer. Every unit of solar you use on site replaces electricity you would otherwise buy at the full commercial rate, which averaged about 24p per kWh (kilowatt hour, the unit on your bill) in early 2026 according to government figures. Every unit you export earns a Smart Export Guarantee rate that is usually a fraction of that.
So the aim is to match generation to demand. The right system is one whose output your building absorbs during the working day, with modest export at weekends and in high summer. A bakery, a school, a cold store and an air-conditioned office can have identical roofs and need very different systems.
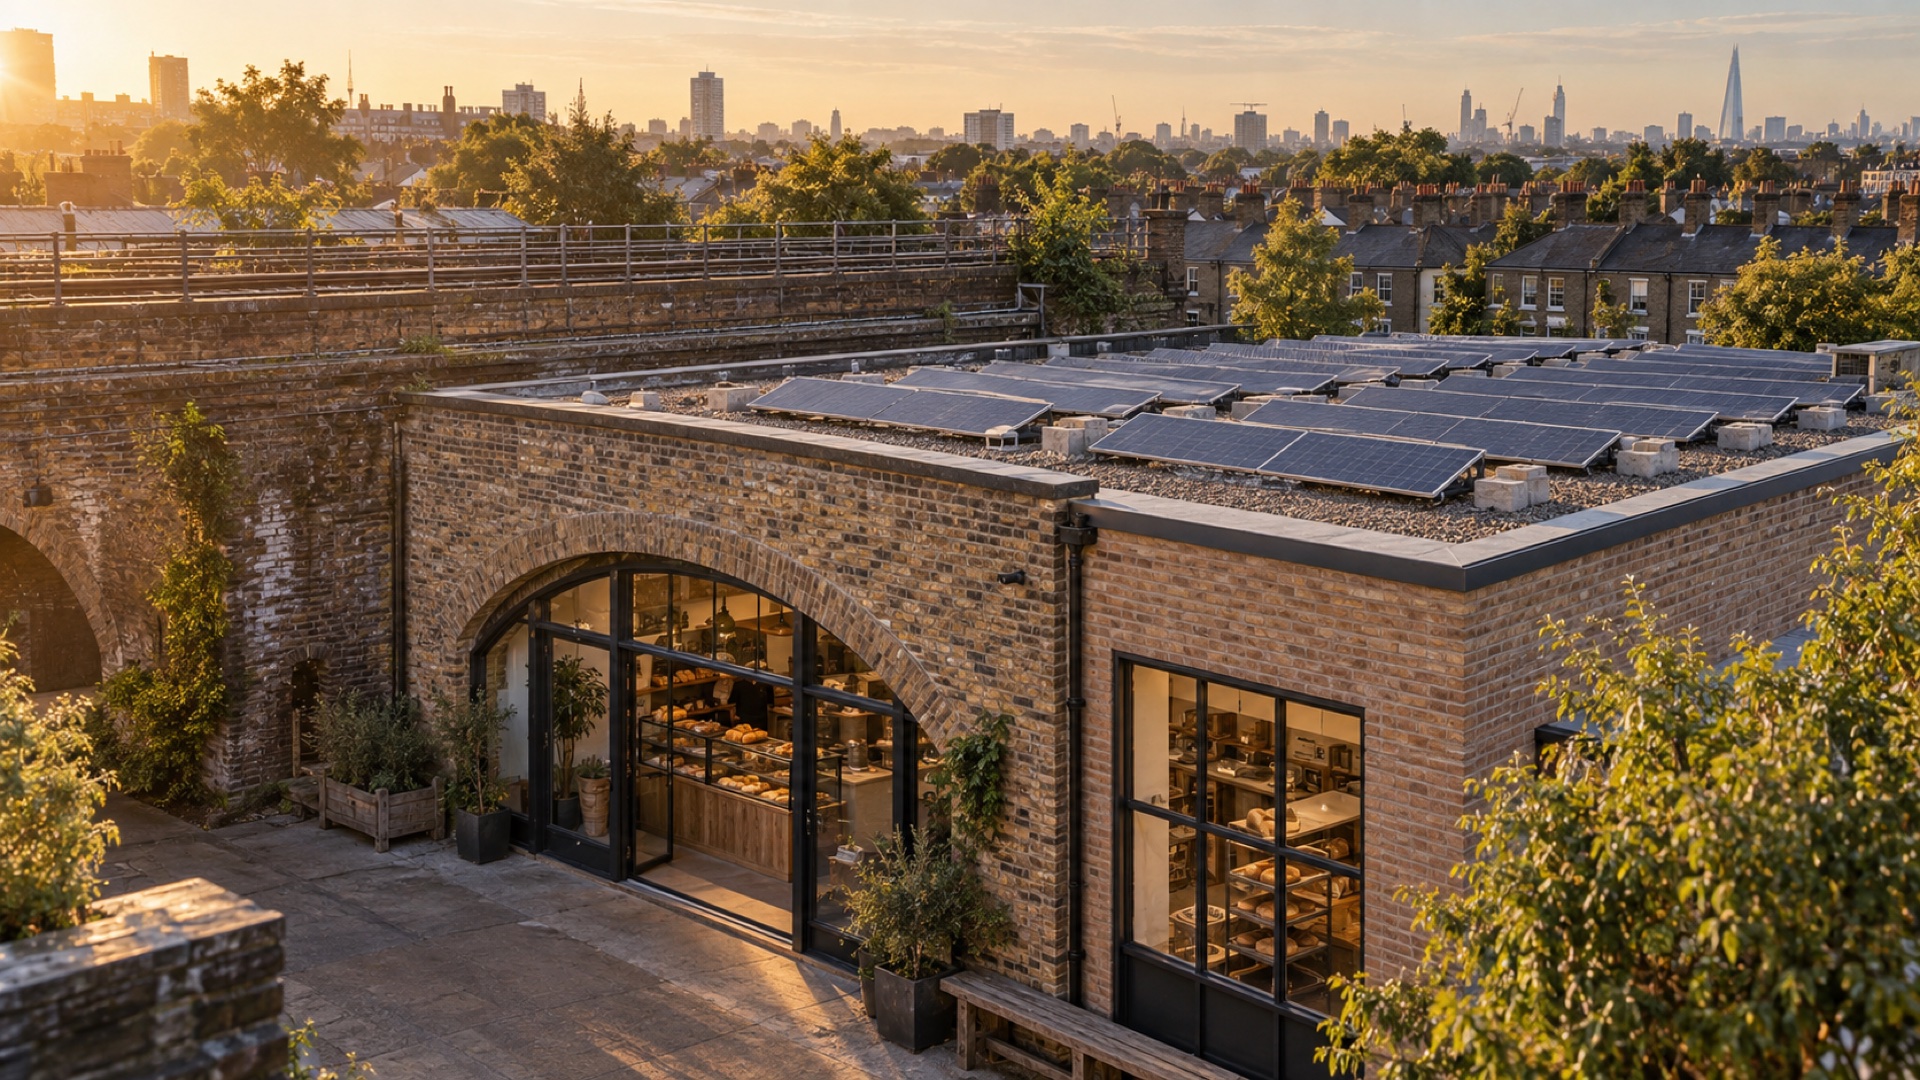
The Peckham bakery shows how this works. Its ovens pull hardest between 4am and 10am, so we sized a 24 kW (kilowatt, a measure of peak output) array to the morning load rather than filling the roof, on an east-west frame that spreads generation from first light instead of peaking at midday. It produced 21,400 kWh in year one, earned £1,140 in export payments, and is on track to pay back in just over four years, without a battery.
Why half-hourly data matters
The best input to a commercial design is your half-hourly consumption data: how much electricity the site used in each 30-minute period, ideally for the last 12 months. Larger sites on half-hourly meters already have it, and most businesses with a smart meter can request it from their supplier. We lay that data over a modelled generation profile for your roof, hour by hour, to see how much solar the site would really use.
Annual totals hide the pattern that decides payback. A site using 100,000 kWh a year mostly at night is a weak candidate for solar without storage, while the same total used between 8am and 6pm is a strong one.
Buy, finance or sign a power purchase agreement
There are three common ways to pay:
- Capital purchase: you pay upfront and keep every saving. It usually gives the best lifetime return and gives you access to capital allowances.
- Asset finance or a loan: spreads the cost. If repayments are lower than the monthly saving, the system is cash positive from the start. Tax treatment depends on the type of finance.
- Power purchase agreement (PPA): a third party funds, owns and maintains the system on your roof and sells you its electricity at an agreed rate below grid prices, typically for 15 to 25 years. There is no upfront cost, but you share the savings and sign a long contract that has to survive a sale of the building or the end of your lease.
At the time of writing, installed prices for commercial rooftop systems commonly fall between about £850 and £1,200 per kW before VAT, falling as the system gets larger. VAT at 20% applies to commercial installations, and VAT-registered businesses can normally reclaim it.
Capital allowances, business rates and a worked example
HMRC lists solar panels as special rate expenditure, which decides the tax reliefs available:
- Annual Investment Allowance (AIA): lets companies and unincorporated businesses deduct up to £1 million a year of qualifying plant and machinery, including special rate items such as solar panels, from taxable profits in the year of purchase.
- 50% first-year allowance: companies paying Corporation Tax can deduct half the cost of new, unused special rate assets in year one, with the balance added to the special rate pool. It mainly matters for spending above the AIA limit.
- Full expensing: the 100% allowance for main rate assets does not apply to solar panels, because they are special rate.
- Writing-down allowance: anything not relieved upfront is written down at 6% a year in the special rate pool.
On business rates, plant and machinery used for onsite renewable generation and storage in England, including rooftop solar and batteries, is exempt from rating until 31 March 2035, so a qualifying system should not raise your rateable value.
Tax treatment depends on your structure, profits, funding method and whether you own or lease the building. Treat this section as background and confirm the treatment with your accountant before relying on it.
Worked example: a 50 kW office roof
Take a 50 kW system at an assumed £1,000 per kW, so £50,000 before VAT. In the Southeast a well-placed array generates roughly 900 kWh per kW a year, so 50 × 900 = 45,000 kWh. If the building uses 80% of that on site, that is 36,000 kWh at 24p, a saving of £8,640. The other 9,000 kWh, exported at an assumed 5p, earns £450. The annual benefit is £9,090, and simple payback is £50,000 ÷ £9,090 = 5.5 years.
If the company claims the AIA on the full cost and pays Corporation Tax at the 25% main rate, the deduction cuts its tax bill by £50,000 × 25% = £12,500. The net cost falls to £37,500 and payback to £37,500 ÷ £9,090 = 4.1 years. This ignores panel degradation, maintenance, inverter replacement and future price changes, so treat it as a starting point rather than a forecast.
Leased premises, landlord consent and the grid connection
If you lease your premises you will almost certainly need the landlord's written consent, because most commercial leases restrict alterations and many exclude the roof from what you rent. Agree early who owns the system, who insures it, and what happens to it when the lease ends. A system that outlasts your lease adds value to the building, which can help the conversation.
The grid connection is usually the longest step. Most commercial systems exceed the G98 limit of 16 amps per phase (about 11 kW on a three-phase supply), so they need G99 approval from the Distribution Network Operator (DNO), the company that runs the local network, before installation. In our experience and in industry guidance, larger applications commonly take two to four months, and longer where the local network needs reinforcement. The DNO may also cap how much you can export, which is another reason to size to on-site demand.
What to ask an installer
- Have you modelled our half-hourly data? Ask to see predicted self-consumption, not just annual generation.
- Who handles the DNO application and structural checks? Both should be in the scope and the price.
- How will the work fit around operations? Overnight, phased or holiday installs should be planned before you sign.
- What changes above 50 kW? Larger systems fall outside MCS certification, so Smart Export Guarantee eligibility goes through Ofgem's ROO-FIT accreditation instead.
- What monitoring and reporting do we get? Finance and sustainability teams will want monthly generation and savings figures.
- What maintenance and response times apply after handover? Check who you call when an inverter faults.
Our guides to the Smart Export Guarantee and whether a battery is worth it cover the export and storage decisions in more detail.
Where to start
Request 12 months of half-hourly data from your supplier and check your lease for alteration clauses. With those two things we can model a system for your site and give your finance director a payback figure built on your own usage. Read more about solar for business, or contact us to arrange a feasibility survey.